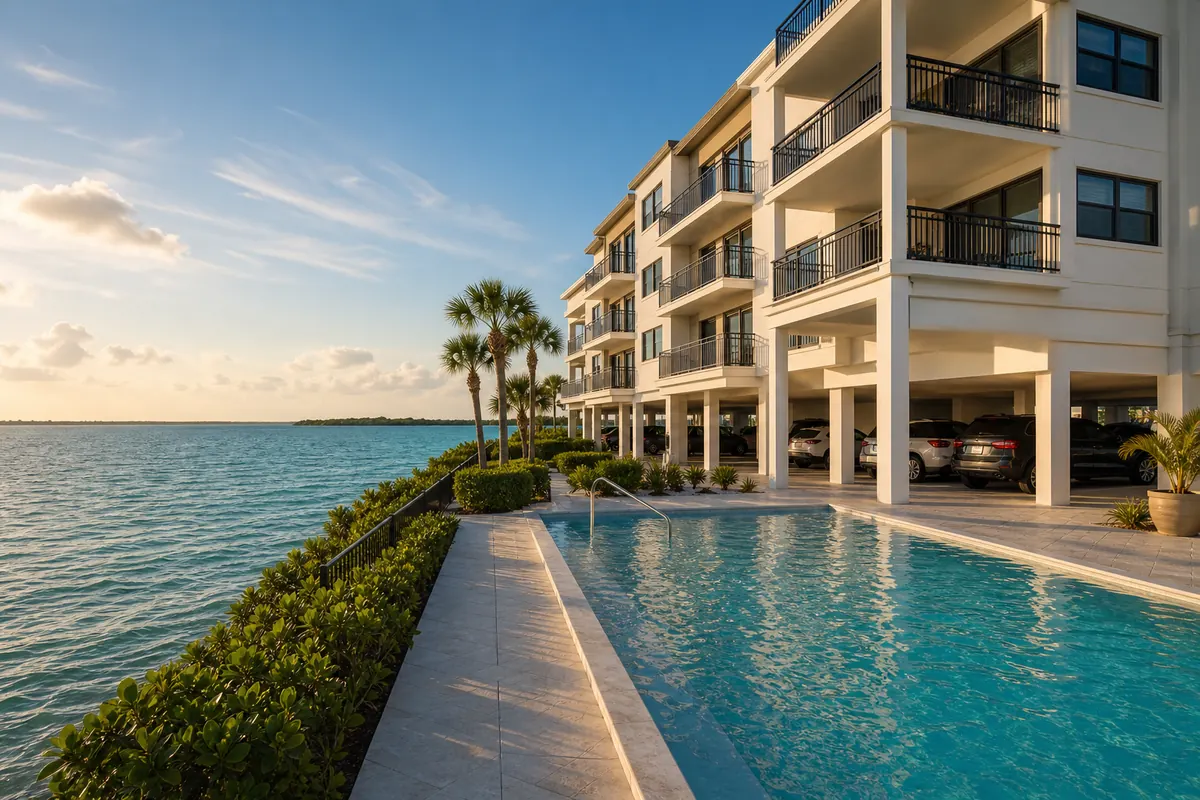
Sarasota Condo Coverage
Condo Insurance in Sarasota, FL
Get clear condo insurance guidance.
What Condo Insurance Does
Many condo owners assume the association policy covers the whole unit. That is often not the case. You still may need your own condo insurance for the parts of the home the master policy does not handle. In Sarasota, that question matters before storm season, before a tenant moves in, and before you update flooring, cabinets, or fixtures. We help you sort out the gap between the association policy and your own HO-6 policy, so you can ask better questions and get a quote that matches how your unit is actually used.
Your situation is usually specific to the building and the unit. A high rise near the bayfront may have different concerns than a garden style community farther inland. A unit used year round may need a different review than a seasonal place that sits empty for stretches. Some owners rent the unit part of the year. Some have made major interior changes over time. We walk through those details in plain language. Then a licensed agent can follow up with options and next steps.
Condo Insurance Across Sarasota County and Nearby
- Sarasota, FL
- Bradenton, FL
- Venice, FL
- Lakewood Ranch, FL
- Osprey, FL
- Nokomis, FL
- Laurel, FL
- Siesta Key, FL
- Longboat Key, FL
- Palmer Ranch, FL
- Fruitville, FL
- Gulf Gate Estates, FL
- Sarasota Springs, FL
- Bee Ridge, FL
- Kensington Park, FL
- The Meadows, FL
- South Sarasota, FL
- Bayshore Gardens, FL
- South Bradenton, FL
- Oneco, FL
- Lido Key, FL
What to Review First
Start with the association master policy. That document usually sets the line between what the building covers and what belongs on the unit owner's policy. In Sarasota, it also helps to review storm deductibles, flood exposure, vacancy periods, and whether the unit is ever rented out.
Master policy vs walls-in
An HO-6 policy is built for a condo unit owner. It generally works alongside the association's master policy, not in place of it. The key question is where the association stops. Some master policies may cover only common areas and the building structure. Others may include more. Your own policy may need to cover interior walls, flooring, cabinets, built-ins, fixtures, and other parts of the unit that fall to you under the condo documents.
Interior improvements
Upgrades inside the unit often change what should be insured. If you replaced standard finishes with custom flooring, stone counters, better cabinets, or updated bathroom work, those improvements may need to be reflected in the policy. That matters after a covered loss when repair costs are based on what is actually there now. Owners sometimes assume the association policy adjusts for those changes. It often does not.
Personal property
Your furniture, clothing, electronics, kitchen items, and similar belongings are separate from the building itself. Condo insurance may help cover personal property after certain covered losses, subject to the policy terms and deductible. This is especially important for owners who keep a furnished seasonal unit in Sarasota. Storm damage, fire, theft, and water-related claims can raise questions fast. A clear inventory and realistic limits can help avoid a shortfall.
Loss assessment and liability
Condo policies may include loss assessment coverage, which can matter if the association charges unit owners after a covered problem affecting common property. Liability coverage is another part to review. It may help if someone is injured in your unit or if you are held responsible for certain property damage, depending on the facts and policy terms. These areas are easy to overlook because they do not involve the walls or your belongings, but they can still affect you directly.
Loss of use
If a covered loss makes the unit unfit to live in for a time, loss of use coverage may help with temporary living costs, subject to policy terms. That can matter if a kitchen fire, interior water damage, or storm-related issue leaves the condo unusable while repairs happen. For owners who live in the unit full time, this can be a major concern. For seasonal owners, the question may be how long the unit could sit before repairs are completed.
Hurricane deductibles and flood
Storm questions deserve their own review on the Gulf Coast. Wind-related deductibles may be different from other deductibles on the same policy. Flood also needs special attention because it is generally handled by a separate policy, not by a standard condo policy. In Sarasota, units near Sarasota Bay, the bayfront, or close to the bridges toward Siesta Key can prompt owners to ask harder questions about water exposure and where flood coverage would come from.
Seasonal, rented, and building type
How you use the condo can affect coverage options. A unit occupied year round is different from one left vacant for long periods. A unit rented out part of the year may need a different setup than an owner-occupied home. Building type matters too. A high rise may have different association rules, maintenance patterns, and claim concerns than a lower garden style building. We help organize those facts so the quote matches the real use of the property.
Why Choose Us for Condo Insurance?
Clear, Local Guidance
We write for Sarasota owners and the way condos are used here. That includes seasonal occupancy, storm concerns, units near the bay, and communities reached by busy local roads such as US 41, Fruitville Rd, Bee Ridge Rd, and University Pkwy.
Built Around Your Documents
Condo insurance starts with paperwork. We focus on the association master policy, bylaws, and any details about interior responsibility, rental use, and deductibles. That helps keep the conversation tied to your actual building instead of broad assumptions that may not fit your unit.
Licensed Follow Up
You can start with straightforward information here. After that, a licensed agent can review your situation and discuss policy options. That gives you a practical next step if you are comparing quotes, buying a unit, updating coverage, or trying to understand a gap.
How to Review It
Gather Your Papers
Start with the association master policy, the condo bylaws, and any recent insurance summary the association provided. If you have a current HO-6 policy, keep that handy too. Those documents frame the discussion.
Map the Gaps
Compare what the association handles with what belongs to you. Focus on interior surfaces, improvements, fixtures, appliances, personal property, and any liability or loss assessment concerns that may fall back on the owner.
Match Unit Use
Review how the condo is used now, not how it was used years ago. Full-time occupancy, seasonal use, vacancy periods, and any rental activity can all affect what kind of policy setup makes sense.
Check Storm Issues
Look closely at wind deductibles, water-related limitations, and whether flood should be addressed separately. In Sarasota, owners often ask these questions first for good reason, especially near the bay and barrier island routes.
Request a Review
Once the unit facts are organized, ask for a quote review based on the building documents and your actual use. That gives the licensed agent a better starting point and can reduce confusion later.
Check Florida Sources
For official Florida insurance and registration information, check state sources directly. The Florida Department of Highway Safety and Motor Vehicles is the place to verify vehicle rules in Florida. For insurance questions and consumer help, the Florida Department of Financial Services consumer helpline is also a useful source. Condo insurance terms and association documents can be confusing, so it helps to compare what you hear from any quote with what Florida agencies publish for consumers.
What a Policy Costs
Condo insurance pricing depends on the unit, the building, and the coverage choices. There is no single price that fits every Sarasota condo. A unit in a high rise near Sarasota Bay may be rated differently than a garden style unit farther from the water. The age and construction of the building, the association's master policy, prior claims, the amount of interior coverage you need, and whether the unit is owner occupied, seasonal, or rented out can all affect the premium.
Your deductible choices and coverage limits also move the premium up or down. So can optional features such as more personal property coverage, stronger loss assessment limits, or added protection for water-related claims where available. Owners who have made major interior upgrades often need more coverage than owners with original finishes. Vacancy periods, short or long rental activity, and the way the association handles maintenance and repairs may also affect how a policy is priced.
Condo Insurance Questions We Hear
Do condo owners in Sarasota need their own insurance if the association already has a master policy?
Often, yes. The association's policy usually covers the building and common areas to some extent, but it may leave the unit owner responsible for interior items and other exposures. Your own HO-6 policy may help cover personal property, interior improvements, liability, loss assessment, and temporary living costs after certain covered losses. The exact split depends on the master policy and condo documents.
Does condo insurance cover flood damage in Florida?
Usually, flood is handled separately. A standard condo policy generally does not serve as flood insurance. That matters in Sarasota because water exposure can be part of the discussion for units near the bayfront and coastal routes. If flood is a concern, ask how a separate flood policy would fit with your HO-6 coverage and what parts of the unit it may protect.
What does walls-in mean for a condo policy?
Walls-in is a common way to describe the part of the unit that may be the owner's responsibility under the condo documents. It can include interior walls, flooring, cabinets, fixtures, built-ins, and improvements you made after purchase. The exact meaning varies by association. That is why the master policy and bylaws should be reviewed before you assume what your own policy needs to cover.
If we rent our Sarasota condo part of the year, does that change the insurance?
It often can. A unit used as a seasonal home with occasional rental activity may need a different review than a unit occupied only by the owner. Rental use can affect what coverage is available and how a claim may be viewed. It is better to disclose how the unit is actually used, including vacancy periods, than to rely on an owner-occupied setup that may not fit.
Are hurricane deductibles different from other deductibles on condo insurance?
They may be. Many Florida property policies handle windstorm or hurricane claims with separate deductible terms from other covered losses. Because those terms can affect what you would pay before insurance responds, they should be reviewed closely. This is especially important on the Gulf Coast, where owners often focus on wind and storm issues first and only later realize flood is handled separately.
Contact Us Today for a Free Estimate
Ready to review condo insurance for your Sarasota vehicle or property? Tell us what you have and we will follow up.
Free, no obligation